Co-Signing on a Mortgage in Oregon: What to Know
What to Know Before Co-Signing on a Mortgage in Oregon
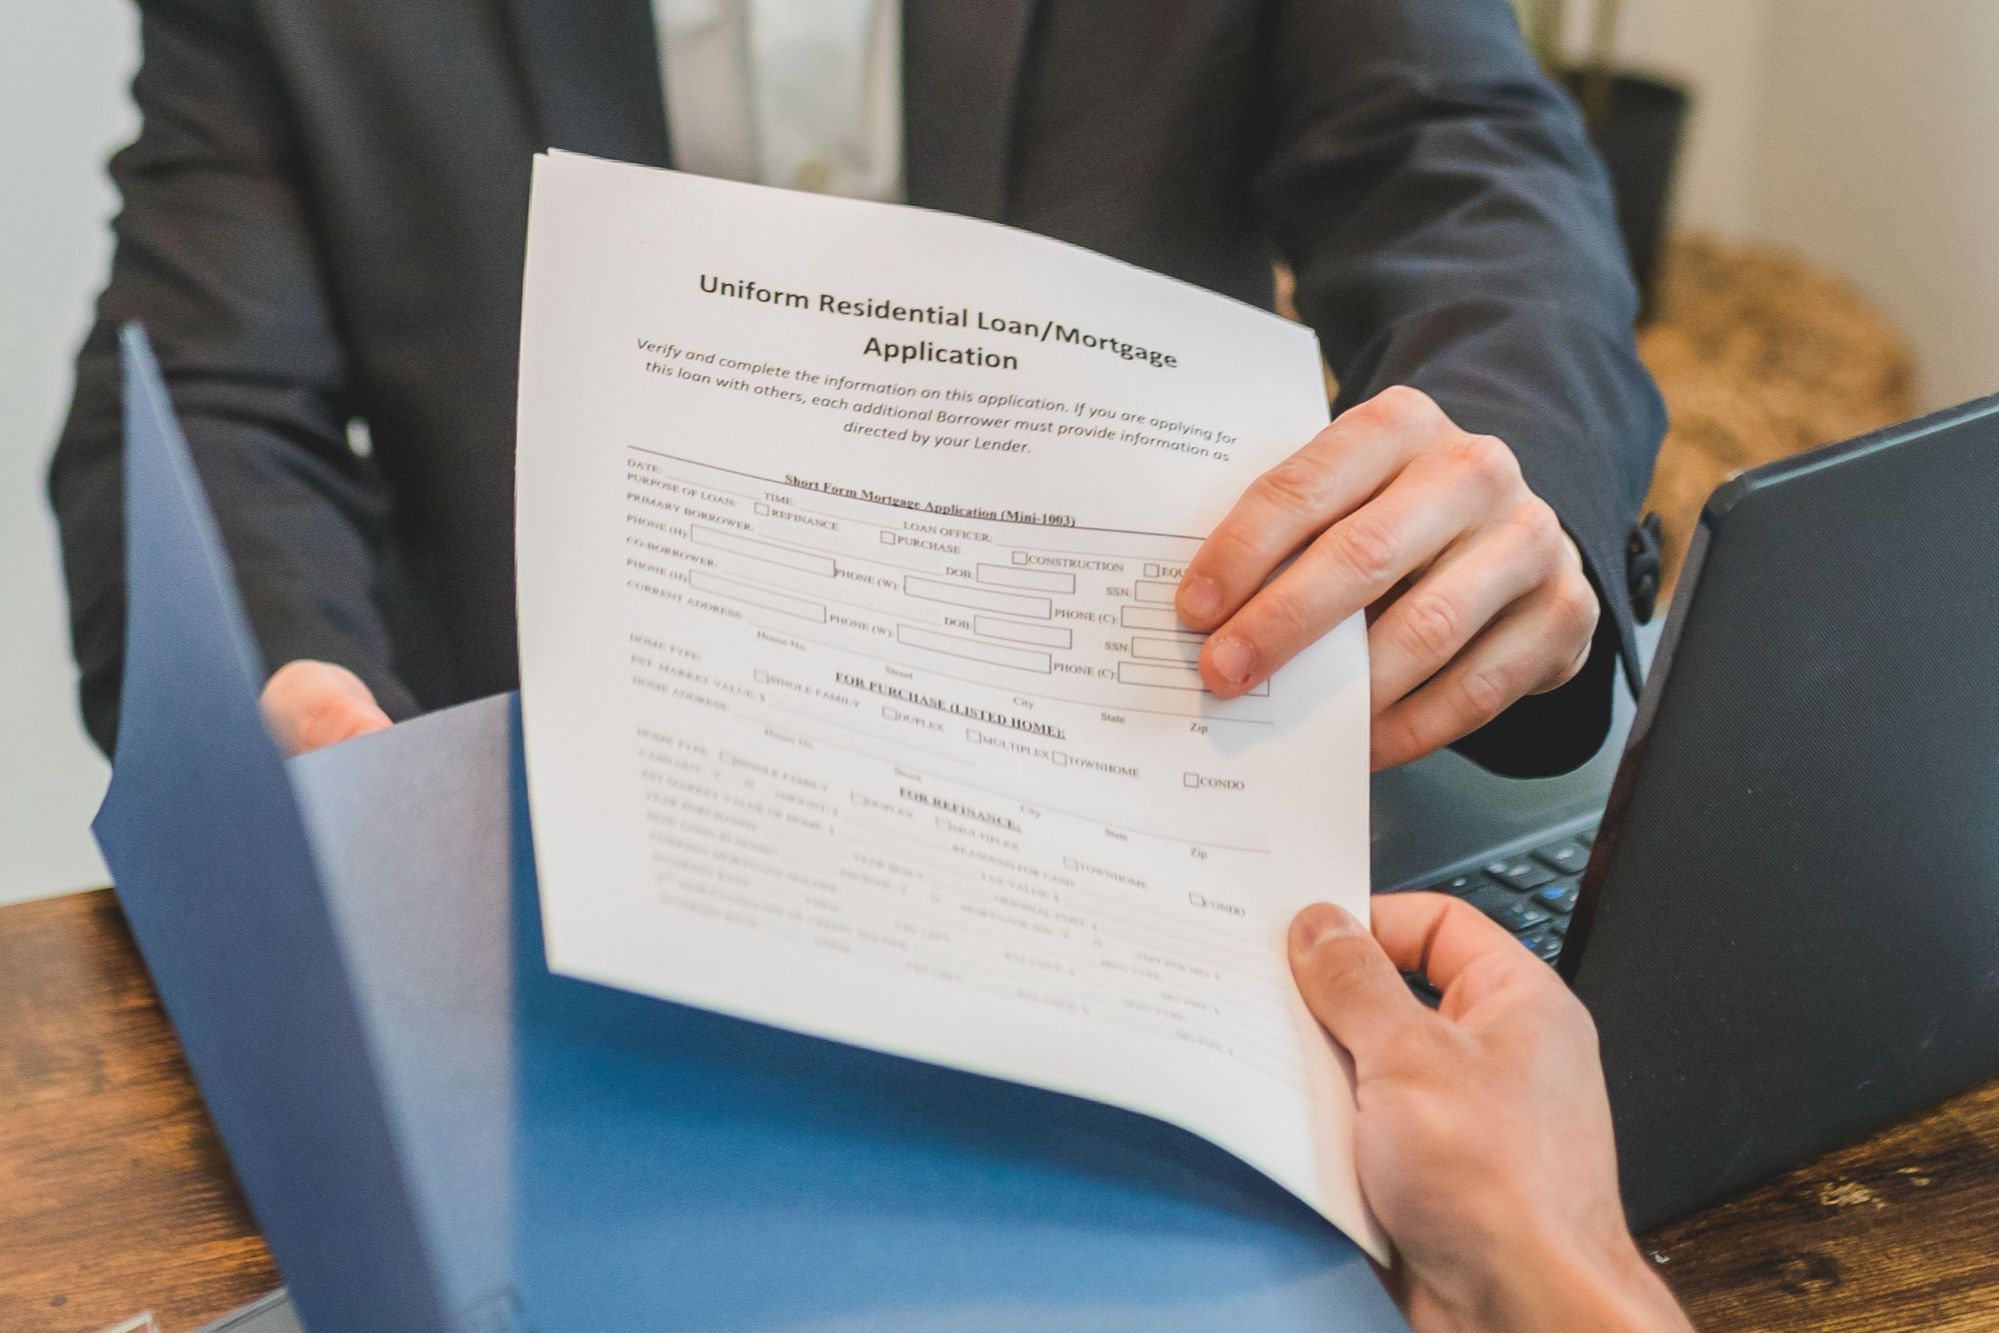
Co-signing on a mortgage means you are agreeing to be fully responsible for the entire loan if the primary borrower stops paying. On a home loan, that usually makes you a non-occupant co-borrower: your name goes on the note, your income and debts are part of the underwriting, and the payment shows up on your credit report as yours. It is not a character reference. It is a loan.
What "co-signing" actually means on a home loan
People use "co-signer," "co-borrower," and "guarantor" as if they are the same thing. Lenders do not. Fannie Mae's Selling Guide treats guarantors, co-signers, and non-occupant borrowers as a specific category, and the rules differ depending on whether the person will live in the home and whether their income is needed to qualify.
For most purchase loans, a co-signer is a non-occupant co-borrower. They sign the promissory note, they are legally obligated for the full balance (not half, not a "backup" share), and the lender can pursue either person for the whole amount. Depending on the loan program, they may also be required to take title to the home. Being on title means you share ownership of a property you may never live in, and that has its own consequences if the primary borrower wants to sell or refinance.
A guarantor is different in some loan types. The guarantor promises to pay if the borrower defaults but is not on the title. Many conventional and government programs do not allow that setup for a typical owner-occupied purchase, so don't assume it is available. Ask the lender which structure they actually permit before anyone signs anything.
How a co-signer changes the loan approval
A co-signer helps when the primary borrower's income or credit is the thing holding back an approval. The lender adds the co-signer's income to the picture, but it also adds the co-signer's debts. Freddie Mac's guidelines, for example, cap the occupying borrower's total debt-to-income ratio at 43% of stable monthly income when a non-occupying borrower is involved, so the person who will live in the home still has to carry a real share of the load on their own.
Down payment and loan-to-value rules tighten up too. Under Fannie Mae's guide, when a non-occupant's income is used to qualify, the maximum loan-to-value generally may not exceed 90% for manually underwritten loans, and the occupying borrower may need to make the first 5% of the down payment from their own funds. Automated underwriting can allow different terms, so the exact numbers depend on the file.
FHA loans add a family-relationship layer. HUD Handbook 4000.1 generally requires a non-occupying co-borrower to be a family member, with a narrow exception for unrelated people who can document a longstanding, substantial, family-type relationship. FHA financing for an occupant with a family co-borrower can still reach 96.5% loan-to-value, but a non-family co-borrower typically means a much larger down payment.
The risks for the person signing
This is the section most people skip, and it is the one that matters most.
- The debt is yours, fully. If the payment is 30 days late, that late payment lands on your credit report too. A single late payment can drop a score meaningfully and stay for years.
- Your borrowing power shrinks. The mortgage counts against your debt-to-income ratio. If you want to buy a home, refinance, or finance a car yourself while you are on someone else's loan, the lender will count that payment against you.
- You can't just walk away. Getting your name off the loan generally means the primary borrower refinances into their own name or the loan is assumed, and either one requires the borrower to qualify alone. A verbal "we'll take you off in two years" has no legal weight.
- Foreclosure can follow you. Oregon limits deficiency judgments after a non-judicial foreclosure on a residential trust deed, but a judicial foreclosure can be a different story, and either way the credit damage is real. If you are asked to sign on a significant loan, a short consult with an Oregon attorney is cheap insurance.
- Relationships are on the line. Money problems between people who care about each other are the hardest kind. Talk through "what happens if" before closing, not after.
What the local market looks like right now
The reason co-signers come up is simple: qualifying is tough. According to Freddie Mac's Primary Mortgage Market Survey, the 30-year fixed rate averaged 7.28% on October 1, 2026, up from 7.03% the week before and 6.34% a year ago. It is the highest reading since October 2023. At those rates, the same loan amount carries a noticeably higher monthly payment than it did last fall, which pushes debt-to-income ratios up.
On the price side, Redfin data shows the Oregon median sale price at $523,118 in July 2026, up 1.6% year over year, with 3,977 homes sold statewide. In Clackamas County, Redfin's recent figures put the median sale price near $650,000. At that level, a monthly payment can stretch a household's qualifying income quickly, which is why some buyers look at adding a co-borrower in the first place.
Alternatives to consider before asking someone to co-sign
Co-signing is one tool, and not always the best one. Before asking anyone to put their credit on the line, it is worth comparing a few options with a lender:
- A co-borrower who will live in the home. If another adult is going to occupy the property, adding them as an occupying co-borrower often gets cleaner terms than a non-occupant arrangement.
- Down payment assistance. Oregon Housing and Community Services (OHCS) runs programs through its Oregon Bond Residential Loan Program, which can lower the cash needed at closing and the loan size you have to qualify for.
- Paying down specific debts first. Eliminating a car loan or credit card balance can improve debt-to-income faster than people expect.
- A gift for down payment. Many programs allow documented gift funds from family. A gift carries no ongoing liability for the giver, unlike a co-signed loan.
- A different loan program. FHA, conventional 97%, and other products treat income, credit, and down payment differently, so one denial does not mean every door is closed.
What this means for you
If you're the buyer asking for help: Be honest with the person you're asking about what could go wrong. Show them the real numbers, the payment, the plan to refinance, and the timeline. Ask your lender to run your scenario both with and without a co-borrower so you can see what the co-signer is actually buying you.
If you're being asked to co-sign: Treat it as if you were taking out the loan yourself, because legally you are. Ask yourself whether you could make the full payment for a year if you had to. Check how it would affect your own plans to buy or borrow in the next few years. And put the exit plan in writing, even if the document is only a shared understanding between the two of you, knowing it is not binding on the lender.
If you're not sure co-signing is even necessary: A conversation with a lender and an agent early, before house hunting, can save a lot of stress. Often there is a path that does not require anyone to put their credit on the line.
This article is general information, not legal, tax, or lending advice. Loan terms vary by lender and program, so confirm the details with a licensed loan officer and an attorney.
Jennifer Schurter serves buyers, sellers, and investors throughout South Clackamas County and the North Willamette Valley — including Canby, Oregon City, Wilsonville, Aurora, Hubbard, Molalla, Woodburn, Newberg, Sherwood, Tualatin, West Linn, Lake Oswego, and the greater Portland metro south. Her goal is simple: to be the most knowledgeable, most responsive, and most genuinely helpful real estate agent in the area — every single time. Jennifer is a licensed Oregon real estate broker with Real Broker LLC.
Ready to talk through your next move? Schedule a time with Jennifer here. No pressure, no pitch — just a real conversation.
Categories
Recent Posts
“I see my job as a Real Estate Advisor is to educate consumers about the realities of the Real Estate market of today. If you're ready to learn more about what it could mean for you to buy, sell, or invest in Real Estate, let's connect!"